When evaluating investment opportunities, headline return figures often get the most attention. But what investors ultimately keep after taxes can matter just as much. That is where post-tax yield comes in.
For real estate investments in particular, the headline dividend can understate what an investor actually keeps. Tax treatment, including return-of-capital characterization and the Section 199A deduction, can improve after-tax outcomes compared with fully taxable income sources. Those outcomes depend on the structure of the investment, the type of income received, and each investor's individual tax situation.
Here’s how post-tax yield can help investors more clearly compare Arrived offerings, including equity funds, credit offerings, and individual properties.
Why post-tax yields matter
The yields investors see advertised are typically shown before taxes. While those figures can be helpful for initial comparisons, they do not always reflect what an investor may actually keep.
How real estate tax treatment can lift after-tax yield
Many Arrived offerings, including the Real Estate Income Fund, individual single family property offerings, the Seattle City Fund, and the Single Family Residential Fund, are structured as Real Estate Investment Trusts (REITs). That structure can unlock tax treatment that can enhance post-tax yields. Two effects matter most, and they show up differently for equity offerings than for credit.
Return of capital on equity offerings
For equity real estate offerings such as the Single Family Residential Fund and individual property offerings, the underlying properties generate depreciation at the entity level. Depreciation can reduce the income a REIT is required to distribute as a taxable dividend, so a portion of what investors receive can be classified as a return of capital rather than current taxable income.
Return-of-capital distributions are generally not taxed in the year they’re received. Instead, they typically reduce an investor’s cost basis and may be taxed later, often at capital gains rates, when shares are sold. For some investors, this deferral can support better after-tax outcomes because taxes deferred today remain invested in the meantime. The portion treated as return of capital varies by year and by offering and is reported on investors’ year-end tax forms.
How credit is different
Arrived's Real Estate Income Fund is a mortgage REIT that invests in loans secured by residential real estate. Its income comes from interest rather than property ownership, so it does not generate property-level depreciation in the same way, and less of its distribution is typically characterized as a return of capital. Its main tax advantage is the Section 199A eligibility on qualified REIT dividends. This is why the credit fund and the equity offerings tell different post-tax stories, and why it helps to compare them side by side.
The Section 199A QBI deduction
Qualified REIT dividends may be eligible for the Section 199A deduction, which allows investors to deduct up to 20% of qualifying REIT dividend income, subject to applicable rules and limitations. This applies to the portion of distributions treated as ordinary REIT dividends across Arrived’s equity and credit offerings.
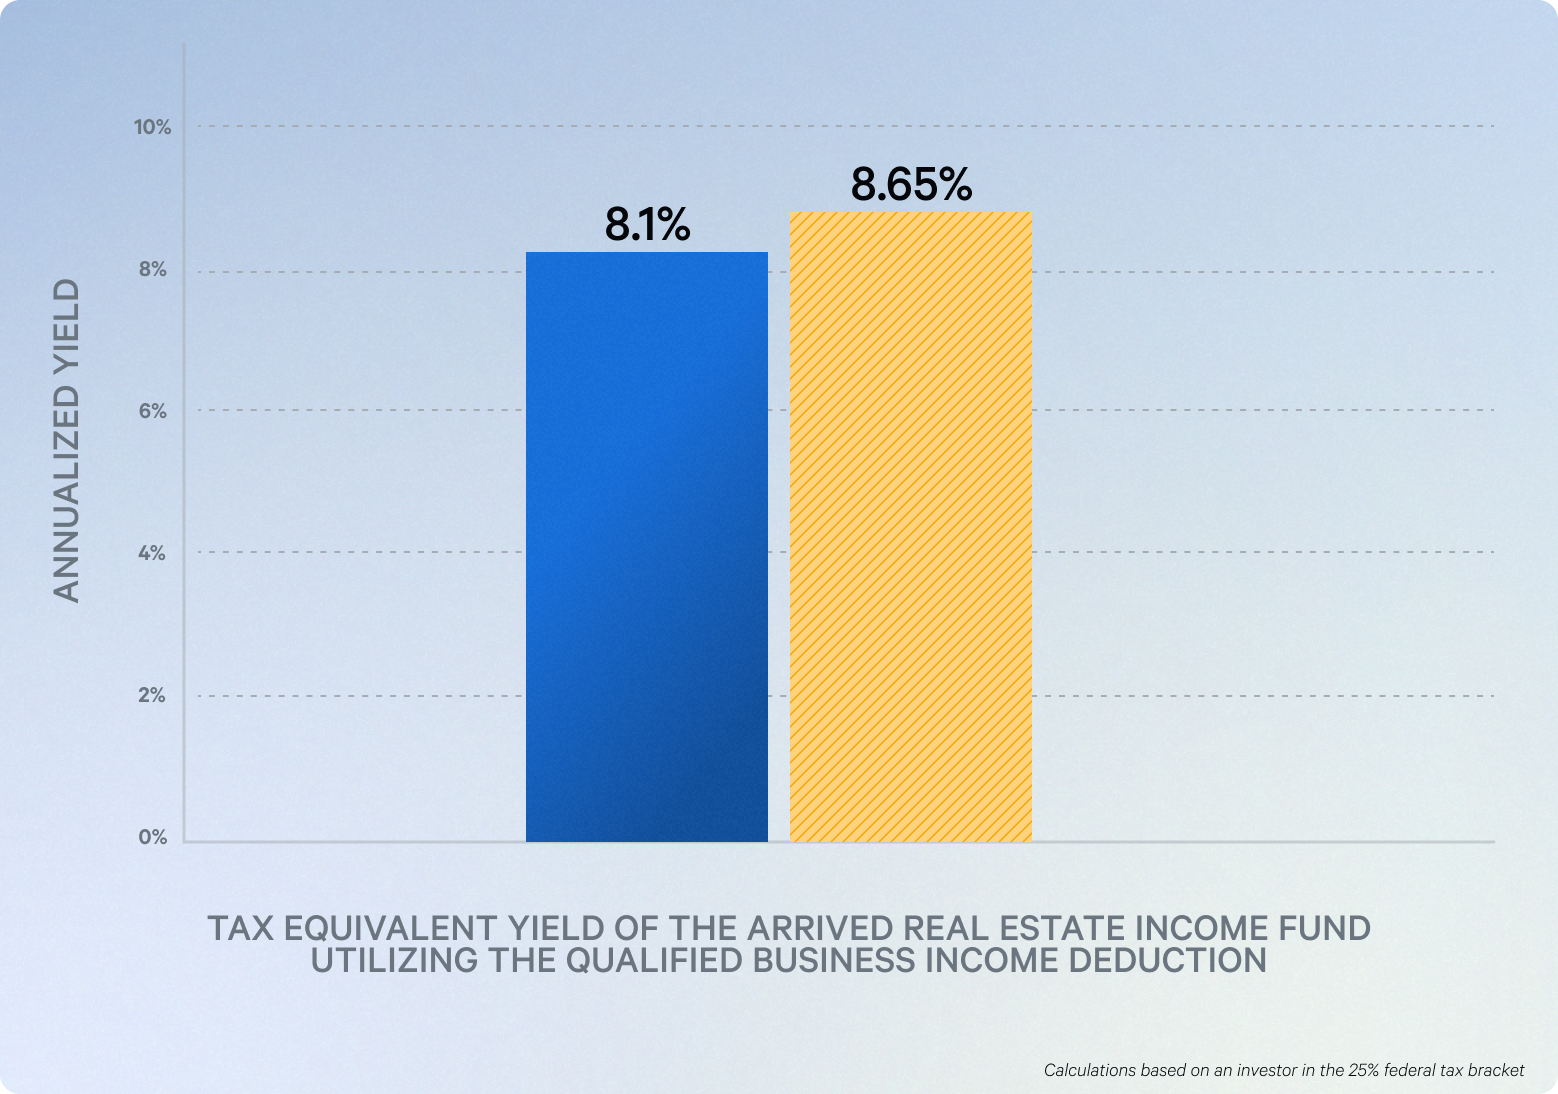
For example, an eligible investor in the 25% federal tax bracket could see an advertised yield of 8.1%¹ effectively increase to a tax-equivalent yield of approximately 8.65% when factoring in the Section 199A deduction.

Comparing post-tax yields to other investments
High-yield savings accounts
Fully taxable at ordinary income rates, these accounts yield far less after taxes. For an investor in the 25% federal tax bracket, a 4.75% yield becomes just 3.56% post-tax.
Real Estate Income Fund
Investments in Arrived’s Real Estate Income Fund with an 8.1%+ historical annualized yield¹ and the 199A deduction result in a post-tax yield of 6.48%. That’s nearly double the post-tax yield of a high-yield savings account, offering a compelling case for these tax-efficient investments.
The Section 199A deduction remains available under current law
The Section 199A deduction was originally scheduled to expire after 2025, but recent legislation made it permanent. As a result, certain qualified REIT dividends may remain eligible for the deduction, allowing eligible investors to deduct up to 20% of that income. The IRS continues to provide guidance and filing forms for claiming the deduction, including Forms 8995 and 8995-A.
Tax treatment depends on the type of income received and each investor’s individual situation, so investors should consult a qualified tax advisor to understand how the rules may apply to them.
Taxes can make a meaningful difference in what investors actually keep. That is why after-tax yield can be an important way to compare income-producing investments throughout the year, not just at tax time.
Pre-tax yield does not always tell the full story. Traditional savings products are generally taxed at ordinary income rates, while real estate investments structured as REITs may receive different tax treatment, including potential eligibility for Section 199A treatment on qualified REIT dividends. Depending on an investor’s tax situation, that difference can meaningfully impact after-tax returns.